Rates. Rewards. Fees. Perks. With so much to compare, choosing the right credit card can quickly become more complicated than expected.
That’s why we’ve done some of the homework for you. We’ve rounded up some of the strongest UK credit cards available right now, based on different spending habits, goals, and lifestyles.
How to Choose a Credit Card
Most credit card lists focus on headline rewards. But in practice, the “best” card is usually the one that fits your habits, works where you shop, and makes your life easier. The best approach is to start with your behaviour.
Before choosing a card, ask yourself:
- How much do I spend each month?
- Will I pay my balance in full every month?
- Do I travel often or mostly spend within the UK?
- Am I looking to earn rewards, save on interest, or build my credit score?
The answers will help point you towards the right card.

Best Everyday Credit Card
If you’re looking for a credit card that rewards your everyday spending, the Lloyds Ultra Credit Card is a strong all-round choice.
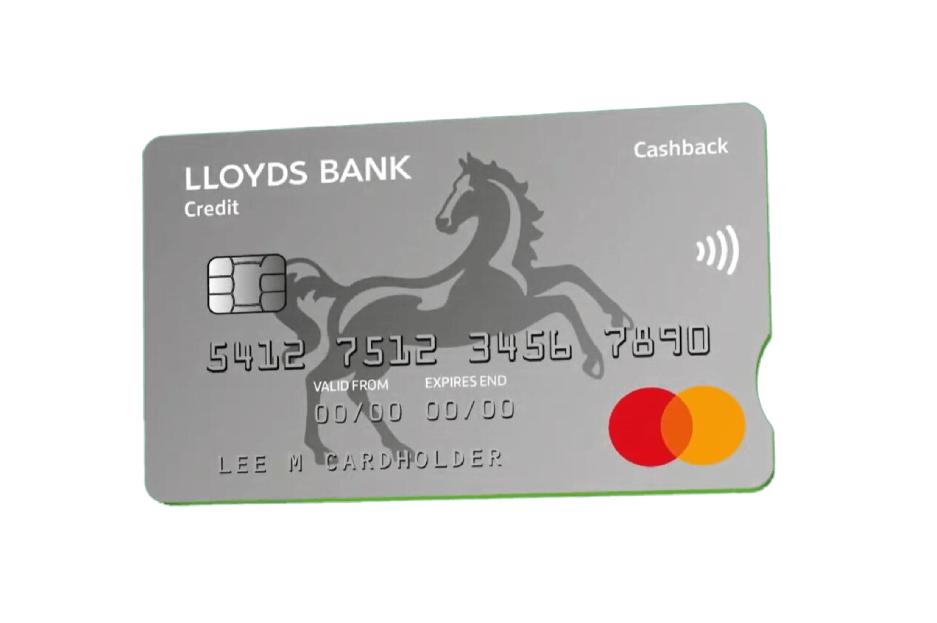
It offers 1% uncapped cashback in your first year, with no annual fee and no foreign transaction fees, a combination that’s rare among mainstream UK credit cards.
Unlike points or airline reward schemes, cashback is straightforward. You simply spend as normal and earn money back on eligible purchases.
After the first year, the cashback rate drops to 0.25%, but the card remains a great option for travel thanks to its fee-free overseas purchases and cash withdrawals.
The Important Details
- No annual fee.
- Uncapped 1% cashback for a year (0.25% after)
- Cashback is paid annually into your account.
- Representative APR: 22.9% variable.
Best Credit Card for Travel
Travelling is expensive enough without paying extra every time you tap your card.
Many UK credit cards charge foreign transaction fees of around 2.99% when you spend in another currency. That might not sound like much, but it quickly adds up. Spend £10,000 abroad over a year and you could pay almost £300 in fees alone.
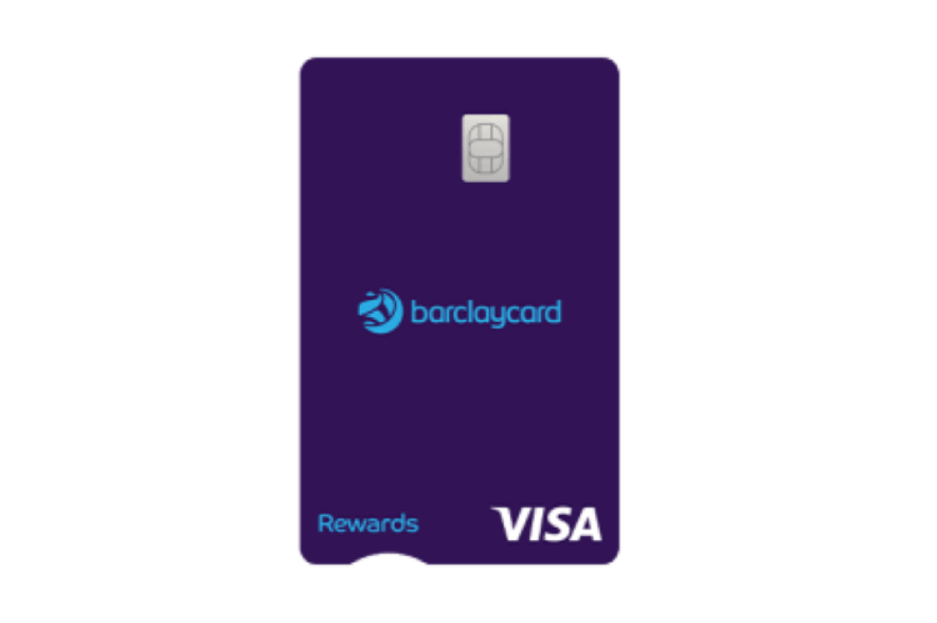
That’s why our pick for the best travel credit card is the Barclays Rewards Card.
The Important Details
- No fixed fees.
- VISA’s competitive exchange rate.
- 0.25% cashback on eligible spending.
- Section 75 protection.
- No monthly card fee.
Best Credit Card for Rewards & Points
If you put most of your everyday spending on a credit card and pay it off in full each month, a rewards card can make that spending work a little harder.
The American Express Rewards Credit Card is a strong option, allowing you to earn Membership Rewards points on everyday purchases without paying an annual card fee. Points can be redeemed across a range of rewards, including travel, shopping and statement credit.
The Important Details
- No annual fee.
- Earn Membership Rewards points on eligible spending.
- Points can be redeemed for travel, shopping and other rewards.
- Best suited to shoppers who pay their balance in full each month.
Best Credit Card for Balance Transfers
If you’re already paying interest on credit card debt, a balance transfer card can give you some breathing room by moving that balance to a card offering a temporary 0% interest period.
The NatWest Balance Transfer Credit Card is worth considering, with an interest-free balance transfer period that can help you focus on paying down your existing balance rather than accumulating more interest.
The Important Details
- 0% interest on qualifying balance transfers for a promotional period.
- A balance transfer fee may apply.
- The standard APR applies once the promotional period ends.
- Best suited to cardholders with a clear plan to repay the transferred balance within the 0% period.
Best 0% Credit Card
A 0% purchase credit card can be a useful way to spread the cost of a larger purchase without paying interest – provided you stay on top of repayments and clear the balance before the promotional period ends.
That’s why the M&S Credit Card Purchase Plus stands out.
The Important Details
- No annual fee.
- Representative APR after the promotional period: approximately 24.9% variable.
- Up to 55 days interest-free credit.
- Earn 1 point per £5 spent at M&S and elsewhere, which will be converted into M&S vouchers for you to spend.
There are a few things to keep in mind. Unlike using a credit card you already have, you’ll need to apply for a new line of credit and approval is subject to your circumstances. You’ll also need to make at least the minimum payment each month to keep the promotional rate. If you still have a balance when the 0% period ends, the standard interest rate will apply.
For shoppers who qualify and manage their repayments carefully, a 0% purchase card can be a cost-effective option. For those who don’t want another credit account, card-linked instalments offer a different approach: merchants can give shoppers more time to pay using the credit they already have.
Best for Building a Credit Score
If your goal is to build or improve your credit history, the Tesco Bank Foundation Credit Card is one of the more accessible and beginner-friendly options available.
It isn’t designed around travel perks or premium rewards. Instead, it’s focused on helping cardholders build a positive credit history through responsible borrowing and repayment.
The Important Details
- Representative APR: 29.9% variable.
- £1,200 credit card limit.
- Earn Clubcard points on spending.
- 1 point for every £4 spent in Tesco.
- These types of cards typically have higher acceptance rates compared to premium rewards or travel cards.
Eligibility Check
Before applying for a credit card, it’s worth doing an eligibility check first.
When you formally apply for a credit card, the lender will carry out a hard credit check. Multiple applications in a short period of time, particularly unsuccessful ones, can impact how lenders view your creditworthiness.
That’s why it’s important to choose a card that suits your circumstances and check your eligibility before applying.
An eligibility check is a soft credit check that gives you an indication of how likely you are to be approved, without affecting your credit score.
Here are some sites that offer eligibility checks:
- Bank of Scotland Eligibility Checker
- MoneySavingExpert Credit Card Eligibility Calculator
- Tesco Bank Eligibility Checker
Eligibility checks are not visible to other lenders and do not affect your credit score.
Where Float Fits In
Millions of shoppers already have access to credit through their existing credit cards. The challenge for merchants is helping their shoppers use that purchasing power when they’re ready to buy – without encouraging them to take on another line of credit.
That’s why merchants are turning to Float.
Float allows shoppers to split any Visa or Mastercard credit card purchases into interest-free monthly instalments using the credit they already have. No new credit applications. No sign up. No new credit issued.
For merchants, that means fewer barriers at checkout, higher basket sizes, and more completed purchases.
In fact, merchants using Float in other markets see an average basket size uplift of 134%* and conversion rates increase by 20–30%*. It’s one of the ways to increase your e-commerce conversion rate.
If you’re curious to see how Float can work for your business, let’s chat.
Savvy Spending
Credit cards can be incredibly useful financial tools when they’re used responsibly. Beyond providing a convenient way to pay, they can help you build a credit history, earn rewards, manage cash flow, and even save money through cashback and travel benefits.
The key is choosing a card that matches your spending habits and financial goals.
Whether you’re looking for everyday rewards, travel perks, a generous welcome bonus, or a way to build your credit score, there’s likely a card that fits your lifestyle.
And remember: the best credit card isn’t necessarily the one with the biggest rewards. It’s the one that helps you manage your money well.
Please note: Promotional periods, fees, and representative APRs can change regularly, so always double-check the latest details before making a decision.
*Standard credit card terms and conditions will still apply. Based on Float global merchant data. UK results may vary.